Broader demand is confirmed.
New-IP momentum persists and overseas weakness eases. Positive earnings revisions could support a re-rating.
Evidence needed Company sales update and dated demand checks.
01 / CONSUMER & CULTURE
9992.HKCan the next wave of characters turn resilient demand into a recovery in the shares?
An independent research proposal
Bloomberg Global Trading Challenge 2026
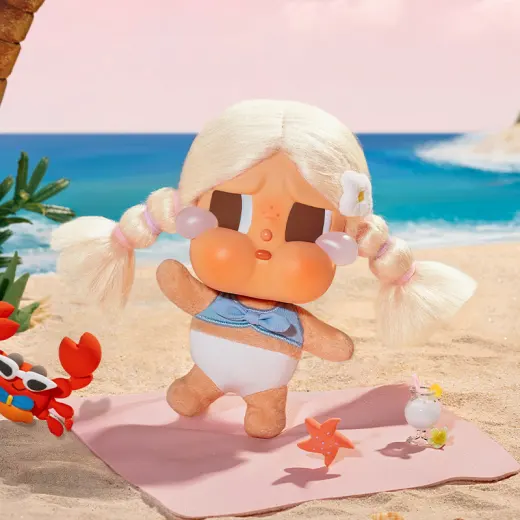
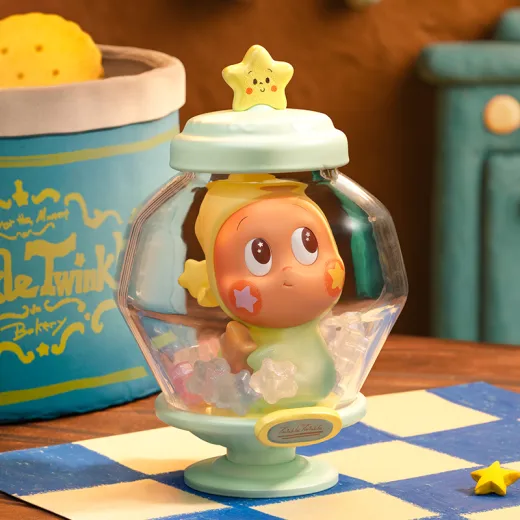
Official product photography · [6]
Our working thesis: CRYBABY and Twinkle Twinkle could broaden growth beyond LABUBU. The next test is whether that strength can offset overseas weakness within the competition window.
Explore the evidence2 Oct 2026 · completed session
Dated snapshot · no automatic refresh [2]
Valuation & sizing pending
CRYBABY +
Twinkle Twinkle
H1 2026 · Share of group revenue, calculated from reported figures. [1]
The two IPs generated RMB4.28bn in H1 2026 revenue combined. Product photographs illustrate the character families; they do not establish sales for the pictured series.
Repeat sell-through across IPs
Growth offsets regional weakness
Evidence changes the market view
02 / THE EVIDENCE
H1 2026 gives the thesis a factual starting point. It does not establish what the market will do next.
H1 ended 30 June 2026 · unaudited · company announcement, 20 Aug 2026, pp. 1, 31. [1]
RMB billions · H1 2025 vs. H1 2026
All bars start at zero; selected IPs only. Company filing p. 30. [1]
Year-on-year H1 revenue change. “China” includes mainland China, Hong Kong, Macao and Taiwan under the company’s segment definition. [1]
Anecdotal interest in CRYBABY and Twinkle Twinkle in Hong Kong and mainland China motivates the demand hypothesis.
Locations, product series, dates and restock volumes are not yet logged. Scarcity may reflect limited supply. [3]
The investment question Are newer IPs creating incremental demand—or rotating spending inside an already popular brand? The contrast with near-flat figurine revenue makes repeated, dated sell-through checks essential.
03 / PRICE CONTEXT
Time spent consolidating is a timing hypothesis. A recovery still needs an earnings or expectations catalyst.
9992.HK / DATED MARKET SNAPSHOT
2 October 2026 close · volume 4,324,247 shares. Unadjusted daily data; no automatic refresh.
Enable JavaScript to explore the inline chart. The available continuous history covers 20 May–2 October 2026, 94 completed sessions.
Read the market-data source note [2]Historical prices and other investors’ activity do not establish fair value or a price floor. Earnings assumptions and an explicit valuation multiple are still needed.
A period of consolidation can frame a timing hypothesis. It cannot establish when expectations will improve or what return a five-week holding period can deliver.
04 / VALUATION DISCIPLINE
This research draft contains no completed valuation. A target would imply precision the research has not yet earned.
No numeric upside, downside or position weight is proposed in this draft.
MODEL REQUIREDH1 EPS is historical, not a full-year forecast. Simply doubling it would be an unsupported assumption.
New-IP momentum persists and overseas weakness eases. Positive earnings revisions could support a re-rating.
Evidence needed Company sales update and dated demand checks.
Strength in selected IPs offsets softer regions. With no material surprise, the share price may remain range-bound.
Evidence needed Reconcile growth by IP, product and geography.
Limited supply explains stockouts, or weaker overseas demand overwhelms newer IPs. The recovery thesis weakens.
Evidence needed Restock depth, inventory and earnings trends.
05 / WHAT COMES NEXT
Five weeks can reward a change in expectations. A sound long-term idea can still miss that window.
Dates from HKU’s 2026 notice; a schedule cross-check, not a complete rulebook. *End converted using America/New_York (EST in November). The notice labels all dates “EDT”; confirm the final cutoff in the organizer’s portal. [4]
Watch for evidence on IP breadth, regional sales and the sustainability of demand. No 2026 Q3 release date has been verified.
A launch covered in Longbridge news. It is an IP-extension signal; no attributable revenue or profit contribution is available. [5]
Reconcile current authorization and recent execution to primary disclosures before treating repurchases as support for the thesis. No numerical buyback assumption is included.
06 / RISK & DECISION
Popular launches and constrained supply are poor proxies for company-wide sell-through.
Check restocks, quantities and repeat purchases.Overseas contraction can offset success in individual characters or locations.
Track regional sales and margin quality.A long investment horizon may not fit the competition’s short return window.
Confirm event dates before proposing exposure.A lower historical price or another investor’s involvement cannot establish mispricing.
Complete the earnings and valuation bridge.POP MART is a candidate for discussion. Before proposing a position, the team needs a valuation, a dated demand log, confirmed competition rules and an explicit invalidation plan.
Review the source notes07 / SOURCES & NOTES
Prepared 5 October 2026. Market snapshots, reported results and observations have different dates and evidentiary weight.
Primary filing · 20 Aug 2026 · period ended 30 Jun 2026 · unaudited. Financial summary p. 1; segments pp. 7–8; IP revenue p. 30; product categories p. 31. Overseas change and chart scales calculated from reported figures.
Open HKEX filing (PDF) ↗ Inspect extracted figures (JSON) ↗9992.HK · HKD · unadjusted closes and actual share volume. 94 continuous completed sessions, 20 May–2 Oct 2026; retrieved 5 Oct 2026 at 05:35 UTC. This is a dated end-of-day snapshot, with no automatic refresh. The original CSV has no opening-price field, so the chart uses a closing-price line.
Renavon publishes its database under CC BY 4.0. Original compilation: Webb-site.com / David M. Webb. Original price/volume provenance: SEHK Daily Quotations Sheets, documented in the compiler’s database schema. Changes: selected the latest continuous segment, sorted dates, renamed fields and calculated price changes and technical indicators. No missing prices or sessions were filled.
The supplied history has a gap between 10 Oct 2025 and 20 May 2026. Older rows are excluded; 6M and 1Y views are disabled. All shows only the 94-session segment. All missing weekdays within that segment correspond to published Hong Kong holidays. Indicators use the loaded history and can differ from providers with longer warm-up periods.
Renavon price history ↗ Inspect this snapshot (JSON) ↗ Provider’s database license ↗ CC BY 4.0 terms ↗ Original data-provenance documentation ↗Indicator methods follow standard moving-average and momentum concepts; calculations here describe the dated series and do not establish fair value.
Fidelity · moving averages ↗ Fidelity · RSI ↗ Fidelity · MACD ↗Research framing dated 5 Oct 2026. Product scarcity is anecdotal and has not been established with a dated store or restock log. Observations are separated from company disclosures and are not treated as measured sell-through.
HKU’s 2026 notice corroborates the five-week period and US$1m simulated starting capital. The full current 2026 rulebook has not been verified. This draft considers shares only. Benchmark methodology, position limits, submission format, AI and confidentiality rules require the current rulebook.
2026 schedule notice ↗ Organizer’s portal ↗5 Oct 2026 article on a 1 Oct launch. Secondary reporting; commercial contribution not disclosed. The event is not assigned a numerical earnings contribution.
Read the report ↗Two representative product images, accessed 5 Oct 2026: CRYBABY “Chilling on the Beach” (Vacation Mode On series) and Twinkle Twinkle “Star Candy” (Savor the Moment series). Shown for identification and research commentary. Revenue figures refer to the entire IP family, not these products. Images and characters belong to their respective rights holders. This independent site is not affiliated with or endorsed by POP MART or Bloomberg.
CRYBABY official product page ↗ Twinkle Twinkle official product page ↗AI-assisted research organization, source checking and presentation. Public discussion draft; not a competition submission or an investment recommendation. Valuation and position sizing remain incomplete. Confirm the current organizer and university rules before any submission.